

Yes, if it is sitting in a basic savings account. Singapore households held S$714.2 billion in currency and deposits at the end of June 2026, more than their entire CPF balances, while headline inflation climbed to 2.3% in August. Money earning a bank's 0.05% base rate is quietly losing around 2% of its purchasing power a year.
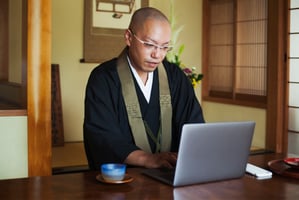
That is the same maths that pushed Japan's Buddhist priests into the market.
Why are Japanese temples investing at all?
Koukyo Yoneta, a fifth-generation priest at Kongo-ji temple in Hokkaido, faced roughly ¥25 million (about S$200,000) in repairs and a congregation that could not give more. So he invested what they had already donated. According to Bloomberg, his mix of US Treasuries, Japanese REITs and stocks including BYD and Hyundai returned more than 10% a year over two years, enough to cover part of the bill and expand the renovation.
He is not alone. Japan's Buddhist population has fallen about 14% in two decades, families spend less on funerals, and a 2021 survey of 7,000 temples found half earn under ¥4 million (around S$32,500) a year. Even the Soto-shu sect, which oversees about 15,000 temples, now holds roughly 10% of the ¥13 billion it manages in Japanese government bonds. Bank of Japan data shows non-profits held about ¥5 trillion of corporate bonds as of March, double the 2023 level.
Some resist. Daian-ji in Nara keeps most assets in cash, calling its approach "purely defensive". And the Koyasan Shingon-shu sect reported losses on structured bonds back in 2013, a reminder that "invest the reserves" is not automatically a happy ending.
How much is idle cash actually costing Singaporeans?
Singapore's Department of Statistics puts household financial assets at S$2.2 trillion as of the second quarter of 2026. Of that:
- Currency and deposits: S$714.2 billion
- CPF balances: S$688.9 billion
- Shares, securities and unit trusts: S$445.7 billion
Roughly a third of household financial wealth sits in cash and deposits, more than in CPF. Some of that is emergency funds or a home downpayment. A lot of it is simply parked.
The arithmetic is unforgiving. The base interest rate on a DBS, POSB or OCBC savings account is 0.05% a year. With CPI-All Items inflation at 2.3% in August 2026 and MAS Core Inflation at 2.2%, its highest in around two years, S$50,000 left at the base rate loses about S$1,100 of purchasing power every twelve months. MAS and MTI have also signalled that core inflation is likely to stay elevated into 2027. The temple priests' problem, rising costs against flat income, is the same one a savings account faces.
What are the low-risk alternatives right now?
The monks' answer was mostly government bonds. Singaporeans have a similar set of instruments, and the numbers have moved this month:
- 6-month T-bill: 1.92% cut-off yield at the 24 September 2026 auction, its highest this year after the US Fed's rate hike
- Singapore Savings Bond (October 2026): 1.65% in year one, 2.32% average over ten years, redeemable any month without penalty
- Fixed deposits: several banks now offering up to about 2% a year on promotional tenors
- CPF: 2.5% on the Ordinary Account, 4% floor on Special, MediSave and Retirement Accounts, now guaranteed through 31 December 2027
Only CPF's 4% clears 2.3% inflation comfortably, but every one of them beats 0.05%. TFC's breakdown of October's SSB rates against T-bills covers how to match each to when you need the cash back, and Chills with TFC's conversation with MoneyOwl's Chuin Ting on using bonds to strengthen a portfolio is still a useful primer on why bonds deserve a place at all.
Should you go further than bonds?
Yoneta's 10% return came from stocks and REITs, which carry real risk. Singapore has its own REIT market, and TFC's guide to Singapore REITs walks through gearing, sponsors and interest-rate sensitivity before you treat a yield as income. The temple lesson is not "buy what the monk bought". It is that holding cash is also a decision with a cost, and the Koyasan episode shows what happens when you chase yield without understanding the product.
A sensible order: keep three to six months of expenses liquid, move anything beyond that into T-bills, SSBs or fixed deposits, then decide whether longer-term money belongs in CPF top-ups, bonds or the market based on your own timeline and risk appetite. This is education, not personal advice.
In summary
Japan's temples are investing because donations shrank while costs rose, and cash could no longer carry them. Singaporeans face a milder version of the same squeeze: S$714 billion in deposits, a 0.05% base rate, inflation at 2.3%. The monks' first move was government bonds, not speculation. That is a reasonable place for idle Singapore cash to start too.
For more considered takes on where your money should sit as rates and inflation shift, follow Chills with TFC and join the community via linkin.bio/thefinancialcoconut.
FAQ
-
Why are Japanese Buddhist temples investing their donations?
Donations and funeral income have fallen as Japan's Buddhist population shrank about 14% over two decades, while inflation pushed up maintenance costs. Temples such as Kongo-ji in Hokkaido now invest reserves in bonds, REITs and stocks to fund repairs. -
How much cash do Singapore households hold?
S$714.2 billion in currency and deposits at the end of the second quarter of 2026, according to the Department of Statistics, more than the S$688.9 billion held in CPF and around a third of total household financial assets. -
Is a savings account losing money to inflation in Singapore?
At a 0.05% base rate, yes. With headline inflation at 2.3% in August 2026, cash at the base rate loses roughly 2% of its purchasing power a year unless it qualifies for bonus interest. -
What is the safest way to earn more than a savings account in Singapore?
Government-backed options include the 6-month T-bill at 1.92%, the October 2026 Singapore Savings Bond at 1.65% in year one, and CPF's 2.5% and 4% rates. Each has a different lock-up period, so match the instrument to when you need the money.
References
- Bloomberg (via Yahoo Finance), Cash-Strapped Japanese Monks Turn to Investing as Inflation Worsens
- The Japan Times, Cash-strapped Japanese monks turn to investing as inflation worsens
- Singapore Department of Statistics, Household Sector Balance Sheet, 2Q 2026
- Singapore Department of Statistics, Consumer Price Index, Latest News and Data
- Yahoo Finance Singapore, Singapore's Core Inflation Quickens in August as Services, Food Costs Increase
- Human Resources Online, Singapore's core inflation hits two-year high of 2.2% as services, food, and retail costs rise
- MoneySmart, Compare DBS Savings Accounts in Singapore
- Growbeansprout, 6-month T-bill yield jumps to 1.92%, highest in 2026
- Turtle Investor, Singapore Savings Bonds (SSB) Oct 2026: Year 1 (1.65%), 10-Year (2.32%) & Results
- CPF Board, Government extends 4% interest rate floor on Special, MediSave and Retirement Account monies until 31 December 2027
- MissLobang, 10 Best Fixed Deposit Rates in Singapore (September 2026)
Let us know what you think about this topic, and what do you want to hear next.
You can now be our community contributor and make a pitch to have your favourite personality be on our show.
Join our community group and drop us your insights on this topic.
Let us know what you think of this post